retirement-planning
Required Minimum Distributions (RMDs): What Changed in 2025 and Why It Matters for Your Retirement Plan
Fortitude Financial · Aug 18, 2026
Explore critical 2025 RMD updates, including inherited IRA rules, age timelines, and tax strategies to protect your retirement plan and avoid penalties.
Navigating retirement planning requires a clear understanding of IRS regulations, especially when it comes to Required Minimum Distributions (RMDs). As tax laws evolve under the SECURE 2.0 Act, staying informed about annual changes is essential for protecting your nest egg. Significant updates regarding inherited IRAs, penalty structures, and distribution age thresholds take full effect in 2025. Knowing how these adjustments impact your portfolio can help you minimize unnecessary income tax exposure and maintain financial confidence throughout your golden years.
Whether you are nearing retirement age or already taking withdrawals from tax-deferred accounts, understanding current RMD regulations is vital. In this guide, we break down the key updates for 2025, explain how they affect your distribution schedule, and share strategic approaches to help optimize your wealth overall.
Understanding the Core Purpose of Required Minimum Distributions
For decades, traditional Individual Retirement Accounts (IRAs), 401(k)s, and 403(b) plans have allowed investors to contribute pre-tax dollars and enjoy tax-deferred growth. RMDs are the government mechanism designed to ensure that tax-deferred retirement accounts are eventually taxed. Once you reach a designated age, the IRS requires you to begin withdrawing a minimum percentage of your account balance each year.
The calculation is based on your total tax-deferred account balances as of December 31 of the previous year, divided by a life expectancy factor determined by IRS actuarial tables. Because these mandatory withdrawals count as ordinary income, they can push you into a higher tax bracket, trigger higher Medicare Part B and D premiums through Income-Related Monthly Adjustment Amounts (IRMAA), or impact the taxability of your Social Security benefits.
Key Update 1: RMD Starting Age Milestones and Timelines
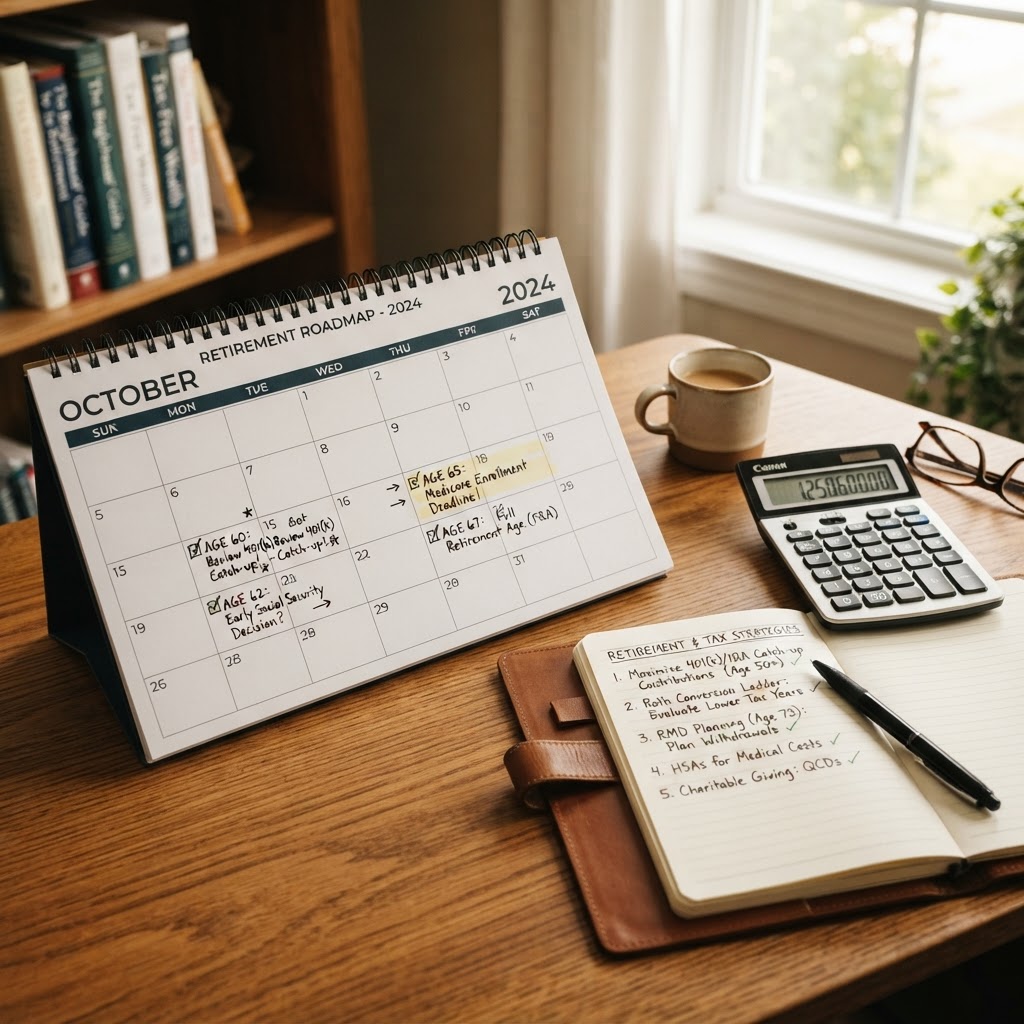
The age at which account holders must begin taking RMDs has undergone notable shifts in recent years. Following the passage of the SECURE 2.0 Act, the starting age increased from 72 to 73 for individuals who reached age 72 after December 31, 2022 (meaning individuals born between 1951 and 1959). If you turn 73 in 2025, your first RMD must be taken by April 1, 2026. However, subsequent annual distributions must be taken by December 31 of each year, including 2026 itself.
Looking further ahead, the starting age is scheduled to jump to 75 in 2033 for individuals born in 1960 or later. Understanding your specific age milestone allows you to coordinate income streams, optimize tax brackets, and delay taxable withdrawals when appropriate.
Key Update 2: Final IRS Rules for Inherited IRAs Take Full Effect in 2025
Perhaps the most significant development for 2025 involves beneficiaries of inherited IRAs. Under the original 2019 SECURE Act, the traditional stretch IRA concept was largely eliminated for non-spouse beneficiaries, replacing it with a requirement to fully distribute the inherited account within 10 years. However, confusion persisted regarding whether annual withdrawals were required during years one through nine.
Following years of temporary relief, the IRS finalized its regulations, confirming that starting in tax year 2025, non-spouse beneficiaries who inherit an IRA from an account owner who died on or after their required beginning date MUST take annual RMDs in years one through nine, in addition to fully depleting the balance by year 10. If the original account owner had not yet reached their required beginning date, the beneficiary is not subject to annual RMDs but must still drain the account by the end of the 10th year.
Key Update 3: Lower Missed RMD Penalties and Roth 401(k) Relief
Prior to recent legislative changes, failing to take a full RMD resulted in a severe 50% excise tax penalty on the unwithdrawn amount. The SECURE 2.0 Act reduced this base penalty to 25%. Furthermore, if the oversight is corrected in a timely manner (typically within two years by filing IRS Form 5329 and withdrawing the required funds), the penalty drops to 10%.
In addition, employer-sponsored designated Roth 401(k) and Roth 403(b) accounts are now exempt from pre-death RMDs, fully aligning them with Roth IRAs. Account holders no longer need to roll designated Roth workplace funds into a Roth IRA simply to avoid lifetime mandatory distributions.
Tax Planning Strategies for Managing Your 2025 RMDs
Managing mandatory distributions effectively requires a proactive tax plan rather than a reactive approach. Here are several time-tested strategies to consider when integrating RMDs into your retirement cash flow:
Qualified Charitable Distributions (QCDs): If you are age 70.5 or older, you can transfer up to $108,000 directly from your traditional IRA to an eligible charity in 2025. A QCD satisfies your RMD requirement (up to the gift amount) without increasing your adjusted gross income, providing a tax-efficient way to support charitable causes.
Systematic Roth Conversions: Converting portion of your traditional IRA assets to a Roth IRA prior to reaching your RMD age allows you to pay income tax on the converted amount during lower income years. This reduces future mandatory distributions and establishes tax-free growth for future years.
Strategic Cash Flow Timing: Coordinating the timing of your initial RMD is essential. Taking your first distribution in the year you turn 73 rather than waiting until the April 1 deadline of the following year prevents doubling up on two RMDs in a single tax year, which could inadvertently drive you into a higher tax bracket.
Partner with Experts to Optimize Your Wealth and Estate
Because tax laws and personal financial situations vary widely, navigating RMD requirements requires tailored advice. Managing mandatory distributions properly ensures that your hard-earned savings continue serving your long-term legacy goals without unexpected tax burdens.
Ready to align your distribution schedule with your broader wealth management goals? We invite you to schedule a personalized retirement strategy session with our team of advisors today. To explore how your IRA assets fit into your overall estate plan, try our complimentary estate planning tool and start taking control of your financial future.
Share this article